A generous season meets payroll and IRS rules
December has a way of making the numbers feel softer than they are. A bonus hits the account, a few extra gifts get added to the cart, and then the paystub shows a withholding spike that doesn’t match what anyone “feels” they earned. The friction usually isn’t the tax itself—it’s timing: payroll rules happen immediately, while personal gift rules mostly show up later, and only if amounts are big enough to matter. If you’re planning meaningful giving and expecting year-end pay, it helps to separate what’s wages from what’s a gift before you start promising money that hasn’t fully settled.
Your employer bonus is wages. It runs through payroll, gets Social Security and Medicare applied (and possibly additional Medicare at higher income), and is subject to federal and state withholding. Withholding can look harsh because many payroll systems treat the bonus like it represents your “regular” rate for the year, even when it doesn’t. That can leave you temporarily cash-tight even if your final tax bill won’t be dramatic.
Personal gifts are different: the recipient doesn’t report them as income, and the giver usually doesn’t owe anything out-of-pocket. The catch is paperwork and tracking when gifts are large, especially if you’re helping multiple people or mixing cash with noncash transfers. In practice, the season goes smoother when you decide up front which dollars are payroll dollars (already taxed and withheld) and which dollars are personal transfers you’ll need to document later.
Personal gifts: when kindness triggers gift-tax paperwork
Once the money is in your checking account, it’s easy to treat every transfer as “just generosity.” The IRS mostly agrees—until totals per person get large enough that a paper trail matters. For 2026, the annual exclusion is $19,000 per recipient, per giver; go over that to one person (even by $1) and you’re generally in Form 709 territory.
This is where people get surprised: filing Form 709 doesn’t automatically mean writing a check. It’s usually a reporting exercise that reduces your lifetime estate/gift exemption, which is much larger than most mid-income households will ever use—but the form is still due on time.
The practical constraint is tracking. Multiple smaller transfers, a forgiven “loan,” or a noncash gift can push a single recipient over the line faster than expected, especially when two spouses are giving from the same pool of funds.
Parents helping adults: tuition, rent, and trips
The next surprise tends to be family support that doesn’t feel like a “gift” at all. Paying an adult child’s rent, covering a security deposit, or sending money for a move is still a transfer to (or for) that person, so it stacks toward the same annual exclusion totals you were trying to track. The constraint is aggregation: three “small” months of help plus a holiday check can push one recipient over the line without anyone noticing.
Tuition is the clean exception when it’s paid directly to the school. If the bill gets reimbursed to your child after they paid it, you’ve turned a tuition payment into a gift. Same idea with medical bills: pay the provider directly or expect it to count toward your gifting limit.
Trips are usually the messiest. Booking flights and hotels as a “family vacation” can morph into paying for one person’s travel, which is a gift, and the receipts matter when amounts are large or split between spouses.
Employee holiday gifts rarely stay “just a gift”
At work, the label matters less than the source. If the “gift” comes from your employer, it usually lands on a pay statement—cash, a gift card, even a “thank-you” paid through payroll. The constraint is that payroll systems are built to treat these as compensation, so Social Security, Medicare, and withholding follow automatically, even when the amount feels like a one-off.
The gray area shows up with noncash items. A modest branded mug might slide by unnoticed, but anything that looks like cash (gift cards, prepaid cards) tends to be treated as taxable wages. The friction is timing: you may not see the tax impact until the next check is smaller than expected, which can squeeze the same budget you were using for personal gifts.
If you’re counting on a “work gift” to fund holiday spending, sanity-check the net amount, not the headline number. The practical move is to keep the paystub or year-end payroll summary so the value doesn’t disappear into a vague “perk” later.
De minimis perks: where the IRS draws the line
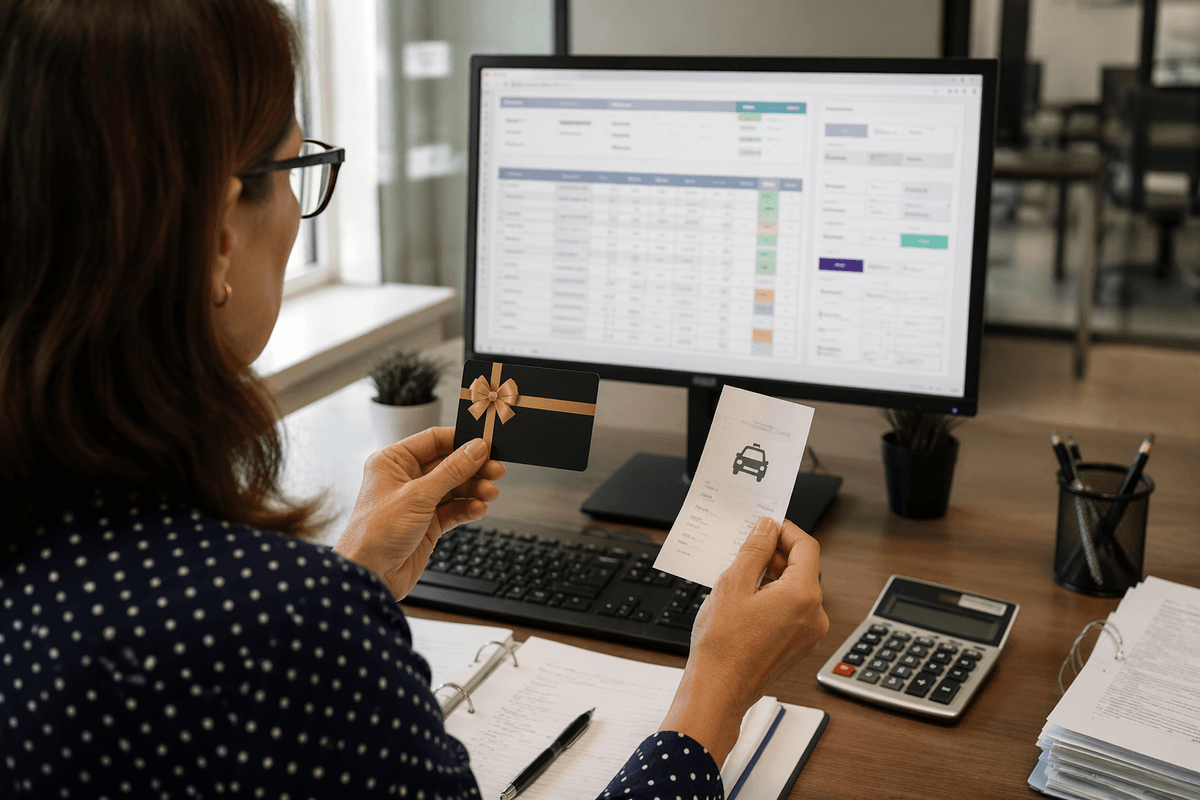
The next thing people lean on is “de minimis,” usually because the item feels too small to bother with. The IRS does allow certain low-value, occasional perks to be excluded when tracking every instance would be impractical. The constraint is frequency: the same small perk given regularly (or to everyone on a schedule) starts to look like compensation, not an incidental freebie.
Cash and cash equivalents don’t fit here. A $25 gift card is still basically cash, so it typically belongs in taxable wages even if it’s framed as a holiday thank-you. Meanwhile, occasional coffee, snacks, a modest holiday turkey, or a one-off local taxi ride after unexpected overtime is closer to the line the IRS tends to tolerate.
In practice, the deciding friction is your employer’s payroll process: if they can easily value it and track it, many will just tax it. That’s a cue to treat anything “gift-card shaped” as net-of-withholding money, not bonus-lite.
Bonuses: the surprise isn’t the tax, it’s withholding
When the real bonus arrives, the first shock is how “expensive” it looks on the paystub. Payroll often withholds federal tax on supplemental wages using a flat method (commonly 22% federally) or by “stacking” the bonus on top of your regular paycheck as if that higher rate lasts all year. Either way, Social Security and Medicare still apply, so the net deposit can come in well below the headline number.
That doesn’t automatically mean the bonus was taxed at your highest bracket. It means cash got pulled forward as withholding. If your household is used to running tight in December—travel, gifts, year-end bills—the timing mismatch is what creates the stress.
Before you spend it, compare the bonus net to what you promised yourself it would fund, then decide whether to leave it alone, tweak your W-4 for next year, or hold a reserve until you see the full-year picture on the W-2.
Noncash awards and gross-ups can cost more than planned
The next kind of “bonus” that catches people is the one that doesn’t arrive as cash: the laptop, the points, the big-ticket raffle prize, the weekend trip. It still has a dollar value, and payroll can add that value to your wages even though nothing new hit your bank account. The constraint shows up immediately: the tax has to come from somewhere, so the next paycheck can shrink more than expected at the exact moment you were relying on it for holiday spending.
Companies sometimes try to smooth this with a gross-up—adding extra pay to cover the taxes on the award. The surprise is how quickly that snowballs, because the gross-up itself is also taxable wages and can pull in withholding plus payroll taxes. If you’re counting on the award to feel like “free value,” check whether it will be imputed income on your paystub, and whether your take-home pay in December can absorb the hit.
Client gifts and business write-offs: limits and proof
By the time client gifts come up, the line between “personal” and “business” is usually already blurred by holiday momentum. The constraint is documentation: the IRS doesn’t care that it felt like goodwill if you can’t show who it was for, when it happened, and why it was business-related. If you’re a W-2 employee, your employer generally handles any deduction mechanics, but receipts and names still tend to fall on whoever bought the gifts.
Even when it is a true business gift, the write-off is capped: the deduction is generally limited to $25 per recipient per year, and shipping, gift wrapping, or engraving can be treated separately if you track them. The friction is that a $150 bottle of wine can be easy to justify socially and surprisingly hard to justify on paper—especially if it was handed out at a dinner where the receipt doesn’t clearly separate the gift from the meal.
The practical move is boring but effective: keep a quick log (recipient, company, date, amount, business reason) and save the proof while it’s fresh. That way the “nice gesture” doesn’t turn into a springtime scramble when someone asks what it was and who got it.